Contact Info
 Ireland
What does an ERP audit consultant do for an Irish company?
An ERP audit consultant reviews a live but underperforming system for an Irish company and reports what is wrong and what to fix first. I compare the configuration with how you trade, check VAT codes, EU listing data and sterling handling for your tax advisor, review user access, payroll journals and integrations, and test which reports finance can trust. It is a remote system health check, not a statutory audit.
Last reviewed by Vikas Saroj
Plenty of Irish companies run an ERP that went live without drama and then slowly lost the confidence of the people using it. Finance rebuilds the monthly pack in Excel, the sterling bank account is reconciled outside the system, and nobody is quite sure which user roles still make sense after the last restructure.
As an independent ERP audit consultant, I work remotely with Irish companies to find out why. I look at the configuration, the data and the daily routines side by side, then write up findings in order of business risk. The review covers VAT setup, access rights, payroll and bank interfaces, reports and license usage.
This is a system health check. It does not replace your statutory auditor, your tax advisor or your data protection advice, and every tax or legal point I raise goes to them for a decision.
 What I Review
Each area ends in written findings with an owner, so the report turns into work rather than sitting in a folder.

I compare how customers, items, price lists and approval steps are configured with how your teams actually sell, buy and invoice today, and note every place where people step outside the ERP to finish a task.

A sample of postings for domestic, Northern Ireland, Great Britain and EU trade, traced to the tax code used and the box it reaches. Your tax advisor judges the treatment; I make the evidence easy to read.

Who can create a supplier, change bank details, approve an invoice and release a SEPA payment run. Conflicts, dormant accounts and shared logins are listed with a suggested fix for each.
How the payroll package, bank files, webshop and group consolidation upload reach the ledger, who notices when a transfer fails and how much rekeying happens around each link.
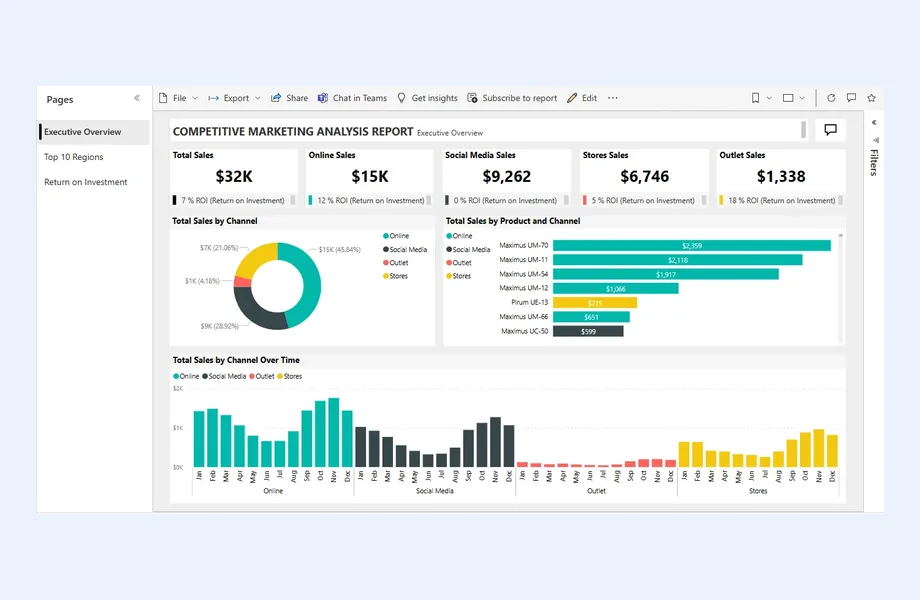
I take the reports used at board and group level, trace their figures back to postings and record where the numbers depend on spreadsheets, manual adjustments or definitions nobody wrote down.
A check of paid users and modules against actual use, then a findings report ranked by business risk and effort, presented to management in a remote readout session.
How I Work
Agree what the review must answer
 Brief with the finance lead
Collect design and process documents
Arrange read-only system access
List advisor and group contacts
Evidence from people and data
Walkthroughs with key users
Sample VAT and sterling postings
Export role and user lists
Trace board reports to postings
Findings ranked by business risk
Draft findings checked with owners
Advisor questions written separately
Readout with management
Fix list with owners
The word audit means something specific in Ireland. Your statutory auditor signs off the annual accounts, and Revenue may examine your tax affairs. An ERP audit is neither. It is an independent look at whether the business system you already run is set up and used in a way that supports how the company works, and whether the data coming out of it deserves trust.
The reasons for asking for one vary. A new finance director wants to understand what they have inherited. A parent company wants assurance before adding another entity to the same database. The board is tired of month-end taking longer every quarter. Or the partner that implemented the system has moved on, and nobody inside the business has a full picture of the configuration.
Whatever the trigger, the method is the same. I agree the questions with you, gather evidence from walkthroughs, configuration and transaction samples, and write findings that each carry a cause, a business effect and a recommended action. Where a finding touches tax, payroll or data protection, I phrase it as a question for the right professional rather than an answer. My ERP health check service sets out the generic method; what follows is the Irish version of it.
Irish VAT setups tend to drift. Codes are added for a new customer type, a template copied from a British sister company brings its own assumptions, and after a while nobody can say which code a sale to a Northern Ireland customer should carry. I do not decide that. I build an evidence pack your tax advisor can review quickly:
The advisor then confirms or corrects, and the correction goes into the fix list as a configuration change. I also note where the system stands on structured e-invoicing. Ireland is following the EU direction toward electronic invoices, with Peppol as a common exchange route for public bodies, so I record what your current setup can send and receive and leave the question of obligations and timing to your advisor.
Access rights in a mature ERP usually reflect the organization chart of several years ago. People change roles and keep old permissions, a contractor login stays active after the contract ends, and a single finance user can often create a supplier, change its IBAN and release the payment run without a second pair of eyes. These are the findings that matter most when money leaves the company by SEPA transfer.
I export users, roles and approval limits, and map them against the duties that should be separated in your business: vendor master changes, invoice approval, payment release, journal posting, price changes and credit limits. Each conflict is listed with the user, the risk and a practical fix, which may be a role change, an approval step or a compensating review by a manager.
The same review raises data protection questions. Who can see payroll journals or employee bank details? How long are customer and staff records kept, and is there any routine for removing them when they are no longer needed? Irish companies answer to the Data Protection Commission under GDPR, but I do not interpret the law. I document what the system holds and who reaches it, then pass the questions to whoever advises you on data protection so retention and access rules are decided by the right person.
An Irish ERP rarely stands alone. A payroll package sends journals, bank statements arrive by file or feed, a webshop or CRM pushes orders, and the parent may collect a monthly upload for consolidation. Each link can fail quietly. I trace every interface: what it sends, how often, which records it creates, who is told when it breaks and how much hand correction happens afterward.
Sterling deserves its own check. Companies that buy or sell in Great Britain often hold sterling bank accounts and customer balances, and revaluation is a common place for workarounds. I look at how exchange rates are maintained, whether unrealized differences are posted by the system or calculated in a spreadsheet, and whether the sterling bank account reconciles inside the ERP.
Then come the spreadsheets. I list every workbook finance and operations rely on each month, ask why it exists and classify the cause: a missing report, a configuration gap, poor master data or simple habit. Some spreadsheets are perfectly sensible. Others exist because the system was never set up to do something it can do, and those become quick wins. Fixing them after the audit is the work described on my ERP optimization page and the spreadsheet replacement guide.
Two more checks round out the review. The first is license usage: named users who have left, users holding a full license for a read-only job, and modules that were bought for a later phase that never happened. I list them so you can raise them with the vendor or partner at the next renewal. The second is report trust. I take the reports that reach the board or the parent, trace a handful of figures back to postings and note where definitions differ between the Irish view and the group view.
The final report is written for management. It opens with a short summary of overall health and the main risks, then lists findings by area, each with a priority, a likely cause and a recommended action. Questions for your tax advisor, auditor or data protection advisor are collected in a separate section so they can be sent on unchanged. I present the findings remotely in a readout with the people who will own the fixes, with visits possible by arrangement.
If the audit shows the system is broadly sound, fixes can run through your existing partner or internal team. If it shows a project still in trouble, the ERP rescue page for Ireland explains the next step. Wider context sits on ERP consulting in Ireland and the Irish hub page.

Tell me about your business and current systems. I’ll suggest the most sensible first step.
Book a Consultation
Not sure which ERP you need?
Share your business requirements with me and I will help you understand the right process, architecture and platform before implementation.
FAQ
No. Your auditor reports on the annual accounts. An ERP audit looks at whether the system itself is configured and used well: process fit, access, interfaces, data and reports. Some findings may interest your auditor, such as access conflicts around payments, and you are free to share the report with them, but it does not replace their work.
No, that judgment belongs to your tax advisor. What I provide is the evidence they need to make it quickly: each tax code in use, sample transactions for every type of trade, the return box each code feeds and the data behind the EU listings. Their answers then become configuration changes in the fix list.
A read-only login covers nearly everything, together with exports of users, roles and selected reports. Walkthroughs happen on video calls where your key users share their screens. I do not need to change anything in the live system, and access can be removed as soon as the review ends.
Yes. The report is yours to share. For an Irish subsidiary I can keep the language and structure suitable for group finance or internal audit, and I can note which findings relate to group reporting templates rather than local configuration. That helps the parent see which fixes belong to the Irish team and which belong to the group.
Every business is different. Share where you are today and what you want to fix, and I’ll tell you honestly whether and how I can help.
Book a Consultation
Insights
 Book a Consultation
Book a consultation to talk through your processes, systems and goals. I’ll reply with practical next steps - no obligation.