Contact Info
 Belgium
Which areas does an ERP audit examine for a Belgian organization?
For a Belgian organization, an ERP audit examines a running system that disappoints and explains why, from outside any vendor. I look at Peppol sending and receiving, CODA statement matching and structured payment references, VAT codes and listing data for your accountant, social secretariat journals, user access, multilingual documents and license use, then rank the findings. It is remote and separate from any statutory audit.
Last reviewed by Vikas Saroj
A Belgian ERP can look fine on the surface and still cost the finance team hours every week. Incoming Peppol invoices wait in a queue, bank lines from CODA files need matching by hand, the accountant corrects VAT codes before each return and nobody is sure which users can still approve payments.
I carry out ERP audits for Belgian companies, associations and service firms remotely, in English. The review compares how the system is configured with how your organization really works, follows real transactions through Peppol, the bank and the ledger, and checks access, payroll journals, reports and licenses.
The output is a ranked list of findings with causes and practical fixes. Anything that touches VAT, payroll law or data protection is framed as a question for your accountant, social secretariat or advisor, who keep the final word.
 What I Review
Every check uses your own transactions, so the findings describe your system rather than a generic standard.
Outgoing and incoming electronic invoices over a recent period: what was delivered, what was rejected, how inbound documents reach the ledger and who deals with exceptions.

How CODA statements are imported and reconciled, how often structured payment references are missing or wrong, and which manual steps finance repeats every week as a result.

Tax codes, return grids, non-deductible portions and the data behind the customer and intra-EU listings, laid out with sample entries so your accountant can confirm or correct them.
How journals from the social secretariat are imported, mapped to accounts and cost centers, and checked, and who in the system can see salary information.

Users, roles and approval limits set against duties that should be split, plus a check that invoices, reminders and order documents exist in each language your customers use.
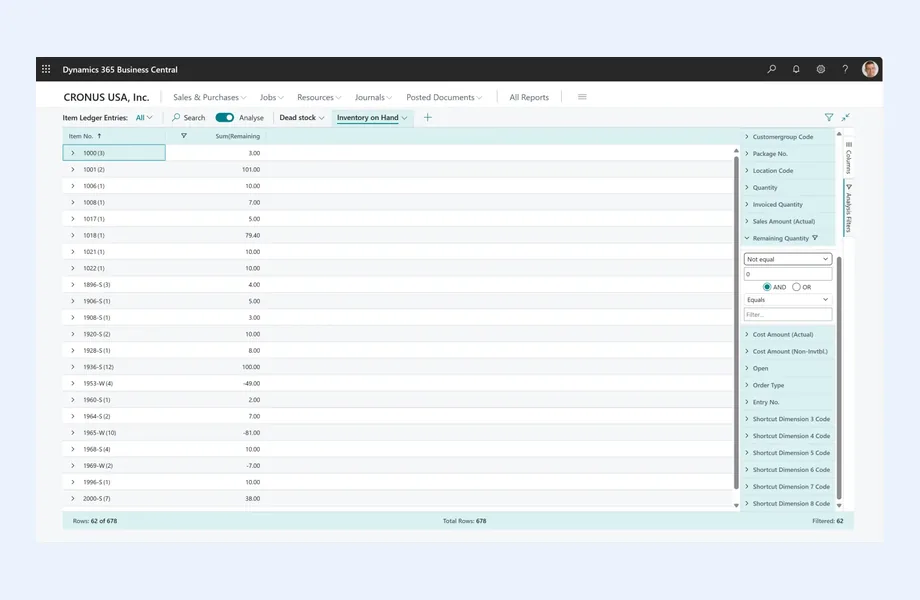
A comparison of paid seats and modules with real activity, followed by findings ordered by risk and effort, presented remotely to management and the people who will own the fixes.
How I Work
Questions, contacts and access
 Agree scope with management
Identify accountant and payroll contacts
Obtain read-only access
Collect Peppol and bank logs
Real transactions, real exceptions
Trace sample invoices both ways
Measure bank matching gaps
Map tax codes to grids
Review roles and templates
Ranked findings with owners
Confirm drafts with process owners
Bundle questions for advisors
Present to management
Agree the fix sequence
Belgian organizations already deal with several kinds of review. An external accounting firm often keeps or checks the books and prepares VAT returns and listings. Larger entities have a statutory auditor who reports on the annual accounts. Subsidies and grants can bring their own controls. An ERP audit sits beside all of these and replaces none of them.
Its question is practical: is the system configured and used in a way that fits how your organization sells, buys, invoices, pays and reports today, and can management trust what comes out of it? The answer comes from evidence. I interview process owners, watch key users work, examine configuration and sample real transactions. Findings are written as cause, effect and fix, and anything that needs a professional judgment on tax, payroll or data protection is passed to the right advisor as a clear question.
Typical triggers include a new finance manager taking over, an accounting firm complaining about the quality of what it receives, an organization that grew from a simple package into a full ERP without revisiting its setup, and the arrival of structured e-invoicing exposing weak master data. The method follows my ERP health check, adapted to Belgian practice as described below. I work remotely and in English, and your bilingual staff guide me through screens and documents in French, Dutch or German.
Belgium has moved business invoicing toward structured electronic invoices exchanged over the Peppol network. Whichever obligations apply to your organization, and from when, is for your accountant to confirm. What I can check is whether the exchange actually works in daily use.
On the outgoing side I review a recent period of invoices and credit notes: how many were delivered over Peppol, how many fell back to email or paper, and why. Common causes include customers without a correct enterprise number in master data, documents missing data the receiving side expects, and credit notes lacking a link to the invoice they correct. Rejected messages are traced to see who was told and what happened next.
On the incoming side I follow supplier invoices from arrival to posting. Do they land in the ERP automatically or in a separate portal that someone checks when they remember? Are they matched to purchase orders and receipts, or keyed again by hand? Is VAT on the inbound document compared with the code the system proposes? Each gap becomes a finding with a likely cause, which may be master data, configuration, the access point provider or simply a missing routine. Where the fix needs integration work, my ERP integration page explains how that is approached.
Belgian bank statements usually arrive as CODA files, while outgoing invoices tend to print a structured payment reference that lets the incoming payment find its invoice without help. When both work, receivables almost reconcile themselves. When they do not, finance spends its mornings matching bank lines by hand.
I review a sample of recent statements and measure, in plain terms, which incoming payments matched automatically, which needed help and why. Typical causes are invoices issued without the structured reference, references generated in a format the matching rules do not recognize, customers paying several invoices at once, and open items migrated as balances that leave nothing to match against. On the outgoing side I check how SEPA payment files and direct debit collections are prepared and approved.
The findings describe each cause and the fix it calls for: a template correction, a matching rule, a master data cleanup or a conversation with the customers who keep paying without a reference. Some of these are quick wins with an immediate effect on the finance team's week. Others belong in a longer improvement plan, of the kind described on my ERP optimization page.
Belgian VAT setups accumulate exceptions: partially deductible costs, vehicles, reverse charge on certain services and works, intra-EU flows and exempt activities in associations. Over time, codes are added and repurposed until the accountant has to correct the return by hand. I do not judge treatment. I prepare an evidence pack that lets your accountant review the setup efficiently:
The same review checks documents. Customers in Flanders, Wallonia, Brussels and the German-speaking community may each expect invoices, reminders and order confirmations in their own language. I list which templates exist per language, whether the customer's language field drives the choice, and where legal mentions differ between versions. The wording itself is reviewed by your bilingual staff or your accountant; the audit makes sure no group of customers is being sent the wrong document.
Most Belgian employers run payroll through a social secretariat, and the ERP receives journals. I check how they are imported, whether accounts and cost centers still match the current chart, who reviews each journal before posting and who in the system can read salary data. The secretariat's own processes are outside the scope; only the handoff into the ERP is reviewed.
Access is reviewed next. Users, roles and approval limits are compared with the separations your organization needs, such as maintaining supplier bank details versus releasing payments, or approving purchases versus receiving goods. Dormant accounts and shared logins are listed. GDPR questions about who sees personal data and how long it is kept are recorded for your data protection contact; the Belgian data protection authority oversees the rules, and I do not interpret them.
Finally, license use: users who left, full licenses for occasional users, modules and add-ons nobody opened. The report then brings everything together: an overview for management, findings ranked by risk and effort, and separate question lists for your accountant, social secretariat and data protection contact. I present it remotely, with visits by arrangement. If the audit reveals a project in real difficulty, see the ERP rescue page for Belgium. The ERP consultant page for Belgium and the Belgium overview cover my other work.

Tell me about your business and current systems. I’ll suggest the most sensible first step.
Book a Consultation
Not sure which ERP you need?
Share your business requirements with me and I will help you understand the right process, architecture and platform before implementation.
FAQ
No, the legal question of what applies to your organization is for your accountant or advisor. The audit shows whether your system actually sends and receives structured invoices reliably, where messages are rejected and why, and how inbound invoices reach the ledger. That gives your advisor a factual basis and gives you a list of practical fixes.
Usually because the structured payment reference is missing, malformed or ignored somewhere between invoice and bank, or because open items were migrated as totals. The audit traces a sample of payments to find which cause applies and how often, so the fix targets the real problem rather than adding another matching rule.
It can be. Associations often have exempt activities, project or grant coding and member invoicing that put particular strain on VAT setup and reporting. The audit checks whether costs land on the right project or grant, whether reports for funders come from the system or from spreadsheets, and whether access to member data is controlled.
The engagement runs in English. Key users can work in their own language interface while we talk, and bilingual colleagues help where documents or screens need explaining. The report is written in English; if parts need to be shared in French or Dutch, your team or a local partner handles the translation.
Every business is different. Share where you are today and what you want to fix, and I’ll tell you honestly whether and how I can help.
Book a Consultation
Insights
 Book a Consultation
Book a consultation to talk through your processes, systems and goals. I’ll reply with practical next steps - no obligation.